Goldman Sachs Sees Eternal Reaching $1 Billion EBITDA by FY29; Raises Target Price to ₹385
Global brokerage Goldman Sachs has maintained its 'Buy' rating on Eternal, the parent company of Zomato and Blinkit, and raised its target price by 11% to ₹385 per share. The previous target was ₹345. (Source: Inkl) The brokerage still counts Eternal among its preferred picks in India's internet sector.
Stock price movement
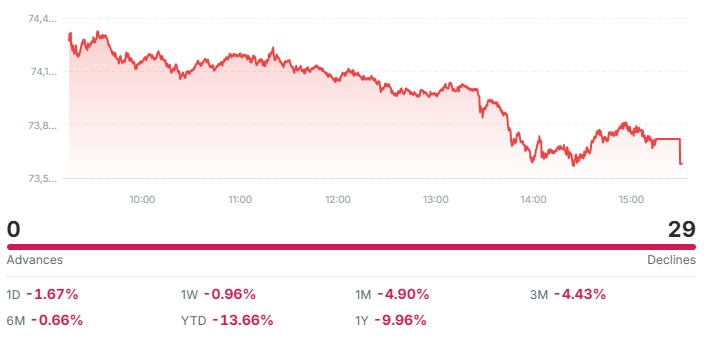
Eternal shares will be in focus on Tuesday, 29 September. The stock closed at ₹331.25 on Monday, and the new target implies an upside of about 16% from that level. (Source: CNBC-TV18) The stock has risen about 28% over the past three months.
Why did the stock move?
The main reason for the move is this brokerage upgrade, not a fresh company announcement. Goldman says that raising the target despite the sharp rally reflects its confidence in earnings per share (EPS) growth.
Company announcement/results
Eternal's results for the quarter ended June 2026 were a mixed bag. (Source: Zee Business) Even so, management is sticking to its goals. In the Q4 FY26 shareholder letter, founder Deepinder Goyal spoke of doubling B2C net order value (NOV) to $20 billion by FY28, and then reaching $1 billion of adjusted EBITDA, hopefully by FY29.
The company expects a 60% CAGR in quick commerce NOV, while food delivery is growing at about 19-20%. The company has also cut its FY27 quick commerce growth guidance to 70% from 100%, and it targets 3,000 dark stores by March.
Brokerage/analyst view
Goldman Sachs has given four reasons for expecting the stock to rise:
1. Growing confidence in the $1 billion EBITDA target. With each quarter, the brokerage has greater visibility into the FY29 target of $1 billion EBITDA, and steady progress could lead to a re-rating of the stock's multiple.
2. Blinkit's growth and margins. The brokerage expects strong growth at Blinkit, steady-state margin expansion and stabilising competitive intensity in quick commerce.
3. Sustained strength in Blinkit's growth. The company's guidance is a 60% NOV CAGR over three years, while Goldman's own estimate is 45%. If Blinkit delivers on the guidance, there is significant upside.
4. Optionality from newer businesses. Newer businesses such as Going-Out offer further upside potential.
Key numbers
| Item | Figure |
|---|---|
| Brokerage rating | Buy (maintained) |
| New target price | ₹385 |
| Previous target price | ₹345 |
| Monday's close | ₹331.25 |
| Potential upside | About 16% |
| Stock over last 3 months | Up about 28% |
| FY29 EBITDA target | $1 billion |
| Blinkit NOV CAGR (company guidance vs Goldman estimate) | 60% vs 45% |
| FY28 B2C NOV target | $20 billion |
What investors should watch next
- Quarterly results: whether each quarter shows clear progress towards the $1 billion EBITDA target.
- Blinkit's growth: whether NOV growth stays close to the 60% CAGR guidance or moves towards Goldman's 45% estimate.
- Competition and margins: whether competition in quick commerce stabilises and how margins improve.
- FY27 guidance: quick commerce growth guidance has already been cut from 100% to 70%, so further updates will matter.
- Valuation: after a rally of about 28% in three months, further upside could be limited.
Sources
- CNBC- Goldman Sachs's four reasons and the upside
Disclaimer: This article is for information only and is not investment advice. Please consult a registered investment advisor before investing.